What is a Cash Flow Statement? Meaning, Types, Importance and Analysis
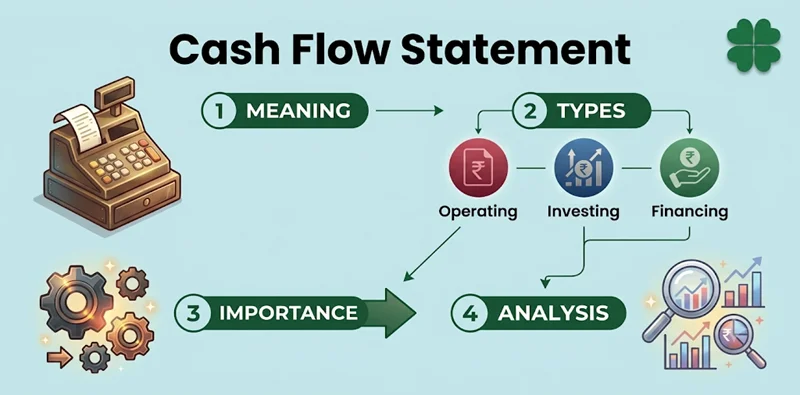
A cash flow statement (CFS) is a financial statement that shows how cash and cash equivalents move into and out of a company during a specific accounting period. It classifies cash flows into three categories: operating activities, investing activities and financing activities.
In simple terms, a cash flow statement helps investors understand where a company gets its cash, where it spends cash, and whether it can generate sufficient cash to meet its financial obligations.
What is a Cash Flow Statement?
A cash flow statement (CFS) is a financial document of a company or a business entity that shows the inflow and outflow of cash in a particular period (usually in a year). This statement shows how much cash the company spends or receives from operational activities. How much cash the company has invested in various assets or collected from liquidating such assets. And how much cash is used to repay debts or used to meet various other financial obligations.
Why Cash Flow Statement is prepared?
A cash flow statement is mainly prepared to know how much cash a company has generated and used for different types of business activities within a particular period. The main purpose of the cash flow statement is to provide relevant information about the company’s cash payments and receipts. Let’s find out what the main objectives of the cash flow statement are and why it is important.
What are the Objectives of a Cash Flow Statement?
The main objective of the cash flow statement is to provide the status of cash inflow and outflow of the company. It shows how the company has spent and generated cash in various activities like business operations, investing in long-term assets and financing activities. And this useful information is very important for stakeholders to evaluate the liquidity and ability to meet its financial obligations.
- Cash Generating Ability: It can evaluate the capacity of the business to generate positive future cash flow from core business operations to make sure daily operations are not affected due to a cash crunch.
- Prevents Account Discrepancies: Another key objective of the CFS is to help reconcile changes in cash balances and identify potential discrepancies in cash records.
- Facilitating Financial Planning: By estimating the current flow of cash in the company, management is able to forecast the budget and financial planning of the company. It can schedule asset replacement, plan the repayment of loans, and other restructuring of long-term debt.
What are the Types of Cash Flow?
The cash flow statement is divided into three sections: operating activities, investing activities and financing activities:
1. Operating Activities
This is the cash generated or used from the core business operations of a company. This cash is usually earned from revenue of the company or interest or stock dividend received, while cash is spent on employee salary and wages, rent, taxes or for paying the utility bills and other day-to-day operating expenses.
The status of positive cash flow from this section shows the capability of the company to generate sufficient cash from its core business operational activities. While a negative cash flow means the company is spending more and collecting less from its core operations.
2. Investing Activities
This section of the cash flow statement shows how much cash is spent or collected from long-term investment or different types of Investment activities. It shows how much cash the company has invested in long-term securities or for acquiring new business or spent on capital expenditure of the company.
While at the inflow end, the statement shows how much cash the company has collected from selling assets or payments on loans and divesting the stake from its subsidiary companies. A negative cash flow from investing activities may indicate investment in assets or businesses for future growth, while a positive cash flow may result from the sale of assets or investments.
3. Financing Activities
This section of the cash flow statement shows how much cash the company has collected by raising funds from selling shares or through long-term debts. It also shows how much cash has been used to repay long-term loans, pay dividends to shareholders or buy back the shares of the company. An increase in debt financing should be analysed alongside the company’s cash generation, debt levels, interest obligations and overall financial position.
On the other hand, Dividend payments and share buybacks represent cash outflows from financing activities. They may reflect how a company chooses to return capital to shareholders, but they should not be viewed on their own as evidence of financial strength. A positive cash flow happens when there are fundraising activities organised during that period, while a negative cash flow may result from cash spent on distributing dividends or repaying debt.
Comparison Table:
| Type of Cash Flow | What It Shows | Common Cash Inflows | Common Cash Outflows |
|---|---|---|---|
| Operating Activities | Cash generated from core business operations | Cash received from customers | Salaries, suppliers, taxes |
| Investing Activities | Cash used for or generated from investments and long-term assets | Sale of assets/investments | Purchase of property, plant and equipment |
| Financing Activities | Cash related to funding the business | Issue of shares, borrowings | Debt repayment, dividends, share buybacks |
Cash Flow Statement Format
A Cash Flow Statement format categorizes all cash inflows and outflows of a business across three core activities: Operating, Investing, and Financing.
Here’s a simple format to understand how the three sections ultimately arrive at the change in cash:
| Particulars | Amount |
|---|---|
| Cash flow from operating activities | ₹X |
| Cash flow from investing activities | ₹X |
| Cash flow from financing activities | ₹X |
| Net increase/decrease in cash | ₹X |
| Opening cash and cash equivalents | ₹X |
| Closing cash and cash equivalents | ₹X |
What are the Methods of Preparing a Cash Flow Statement?
Direct Method: Explains actual cash receipts and cash payments from operating activities.
Indirect Method: Starts with net profit/loss and adjusts for non-cash items, non-operating items and changes in working capital.
How to Read and Analyse Cash Flow Statement?
Understanding the various components of the cash flow statement is important to comprehend how exactly a company generates and spends cash on various activities. A company collects or receives cash from different types of activities during its normal course of business.
Hence, while reading and analysing the cash flow statement, you need to consider whether the company is generating positive or negative cash flow from its various operational business activities.
When analysing a company’s cash flow statement, check:
- Operating cash flow – Is the core business generating cash?
- Trend – Is operating cash flow improving or declining over several periods?
- Capital expenditure – How much cash is being invested in assets?
- Free cash flow – How much cash remains after capital expenditure?
- Financing activities – Is the company raising debt/equity or returning capital to shareholders?
- Cash balance – How has the company’s overall cash position changed?
- Quality of cash generation – Are cash flows supported by sustainable business operations?
- What do Positive and Negative Cash flow mean?
A positive cash flow means the company is receiving more money than it is paying out, generating cash for investment and reducing debts.
While a negative cash flow shows the company is spending more money compared to its receipts, depleting its cash reserve.
Positive operating cash flow – core operations generated more cash than they consumed.
Negative operating cash flow – core operations consumed more cash than they generated.
Positive investing cash flow – could result from selling assets/investments.
Negative investing cash flow – could indicate expenditure on assets or investments.
Positive financing cash flow – could result from raising debt or issuing shares.
Negative financing cash flow – could result from debt repayment, dividends or share buybacks.
Importance of Cash Flow Statement
The cash flow statement is very important to track the movement of cash into and out of the business activities, which include operations, investing and financing activities. It is important to know the liquidity and whether the company is able to generate sufficient cash to maintain its liquidity or not.
- Use of Cash: It is very important to know whether the cash is being used for funding the core business operational activities or used to take loans or invest in long-term assets.
- Ensure Liquidity: Generating enough cash to maintain liquidity is very important to ensure the smooth running of the business without facing any cash crises to meet its day-to-day financial needs.
- Decision Making: Another significance of analysing CFS is to take the right decision in business to use the cash for generating more cash from various business activities.
- Negative Cash Flow: Tracking the cash flow into the business helps to identify whether it is proportionally used and collected from various business activities and assess whether the company is facing a sustained cash deficit.
Cash Flow vs Profit: Key Differences?
Cash flow tracks actual physical money moving in and out of a business. But profit measures what remains of your revenue after subtracting all business expenses using accrual accounting.
| Cash Flow | Profit |
| Focuses on actual cash movements | Includes non-cash accounting items |
| Reported through the cash flow statement | Reported through the income statement |
| Helps assess cash generation and liquidity | Helps assess profitability |
A company can report accounting profit while having negative operating cash flow because revenue may not yet have been collected in cash.
What are the Limitations of a Cash Flow Statement?
A cash flow statement is a valuable financial tool to assess the financial health of the company in terms of meeting its day-to-day operations. However, there are some limitations of this statement, and you also need to understand these limitations to make a well-informed decision while using such an accounting statement.
- Focuses on Cash Movements: A company reporting a net loss can have a positive cash flow; that’s because of non-cash expenses such as depreciation. It shows that this statement only focuses on the cash movement of the company and not on the profitability of the business.
- Lack of Reflecting True Liquidity: A company may have tied up its cash into working capital assets (like convertible inventory or short-term investments) that are not documented in this statement, showing misleading information about the liquidity condition of the company.
- Overlooks Non-Cash Transactions: The non-cash transactions like the acquisition of assets, issuing shares or converting the bonds or preference shares into equity. This shows that non-cash investing and financing activities are completely ignored in the cash flow statement.
- Affects Expansion Plans: Negative cash flow may affect a company’s expansion plans if it is unable to generate sufficient cash to fund its growth. However, investments in expansion may result in higher cash generation in the future.
- Lack of Quality Earnings: With the cash flow statement, you can estimate the quantity of cash flows; it does not show insights of the quality of earnings. For example, a company with positive cash flow from its core business operational activities may still face sustainability concerns if the cash generation is driven by temporary changes in working capital or other non-recurring factors.
Who is required to Prepare a Cash Flow Statement?
Under the Companies Act, 2013, a cash flow statement forms part of the financial statements of companies subject to the applicable requirements and exemptions. The specific exemption criteria should be checked against the current provisions and applicable rules.
While preparing the cash flow statement is not mandatory for various entities Certain companies, including small companies, one-person companies and specified private companies that qualify as recognised start-ups are exempt from preparing a cash flow statement, subject to the applicable conditions.
Conclusion
The cash flow statement is one of the most underrated financial statements that not only shows the inflow and outflow of cash of the company from its daily business operations but also indicates its capability to meet its financial needs for operational, financing and investing activities.
And, it is very important from the perspective of various stakeholders like investors of the company, creditors and other participants to take the right decision while considering the financial health of the company. However, relying only on this statement would not be a wise decision, as it mainly focuses on cash movement and should be analysed along with the income statement and balance sheet to understand profitability, liquidity and the overall financial position of the company.
Frequently Asked Questions (FAQs)
How cash flow statement is prepared?
A cash flow statement is prepared using the balance sheet and income statement of a company for a particular financial year. And to calculate the net change in cash inflow or outflow, cash from all the three activities operating, investing and financing- is calculated and then added to the starting cash balance.
Who prepares cash flow statement?
The accounts or finance department is responsible for preparing the cash flow statement. The individuals working in the company as a senior accountant or financial analyst, under the guidance and monitoring of an experienced chartered accountant, prepare such crucial financial statements.
What is included in cash flow statement?
It includes the incoming and outgoing cash summary from various core business activities such as operating activities, investing activities, and financing activities in a particular period.
What are the uses of cash flow statement?
The cash flow statement is used to track the actual movement of cash in a business for a particular period. One of the main uses is to evaluate the liquidity condition and how cash is used to fund the various business activities and meet its short-term debt obligations.
What is cash flow statement indirect method?
The indirect method of cash flow statement calculates cash flow from operating activities by starting with net profit or loss and adjusting it for non-cash items, non-operating items and changes in working capital.
What is cash flow statement direct method?
A direct method of cash flow statement is used to calculate the actual cash paid and received during a particular financial year. This method converts the accrual-based income statement items into cash-based amounts, giving a more transparent view of operational liquidity of a company.
What are the advantages of cash flow statement?
The key benefits of the cash flow statement are that it evaluates the actual liquidity of the company and distinguishes profit from cash. Apart from this, it also helps to identify financial problems and provide a useful insight to strategically plan budgeting and future expansions of the company.
What are the disadvantages of cash flow statement?
It can track only the movement of cash but fails to reflect non-cash transactions or is not able to measure the overall profitability of the company for a particular period.
Is cash flow statement mandatory for all companies?
Under the Companies Act, 2013, small companies, dormant companies and one-person companies are exempted from preparing cash flow statements.
How depreciation affects cash flow statement?
Depreciation is an accounting method to spread the expense of an asset over a period of years. Though depreciation does not affect the cash flow, in the long term it can absorb some of your taxable income, and on financial records, it can have a positive impact on the cash flow of a company.