Futures positions and option-selling positions in India require upfront margins, generally comprising SPAN margin and exposure margin. Option buyers must pay the applicable premium upfront. Traders who understand how the two parts are formed can better allocate their capital and avoid order rejections. Both parts change with market conditions, so the amount blocked for the same trade can differ from day to day.
What is SPAN and Exposure Margin?
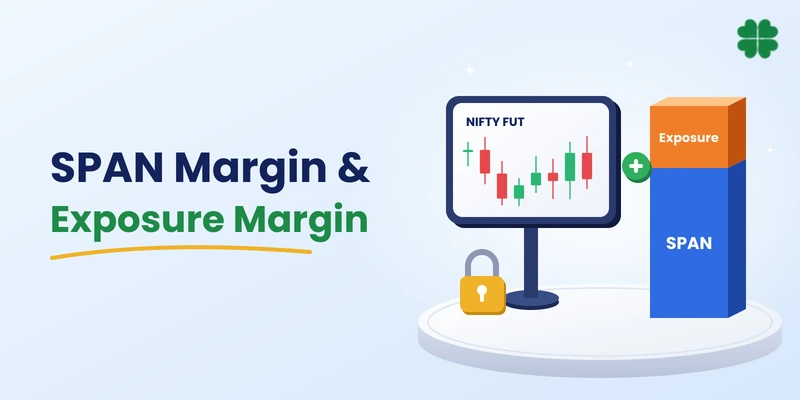
SPAN and exposure margin together make up the upfront margin that a trader must hold for a derivatives position. In the equity derivatives segment, the applicable upfront margin generally comprises SPAN (initial) margin and Extreme Loss Margin (ELM), commonly referred to by brokers as exposure margin. These two components are added together and are not alternatives. However, other applicable margins or obligations may also affect the total amount blocked, depending on the position and contract. Anyone asking “what is SPAN margin and exposure margin” will find that the trading screen shows a single blocked amount, which brokers display as the margin required for the order.
SPAN Margin: The Risk Based Component
SPAN stands for Standard Portfolio Analysis of Risk. It estimates a portfolio’s potential loss under prescribed adverse price and volatility scenarios, and because it works at portfolio level, eligible offsetting positions can lower the requirement.
NSE Clearing calculates the risk parameters for Indian equity derivatives and distributes them to members. The method values each position across a fixed grid of 16 scenarios that move the underlying price and implied volatility, and the scenario with the largest net loss becomes the scanning risk.
Smaller charges, such as one for calendar spread risk, can be added. The parameters are refreshed during the day, so the SPAN figure for the same position can change between morning and afternoon.
Exposure Margin Meaning
The exposure margin meaning is simple. It is an extra amount charged on top of SPAN to cover risks that the scenario grid may not fully capture. The exchange formally refers to this component as Extreme Loss Margin (ELM). It is calculated as a percentage of the notional contract value.
The applicable rate differs between index and stock derivatives and may vary for specific positions. Exposure margin rates differ between index and stock contracts and are revised by the exchange, so the live figure should be taken from the broker’s margin calculator and not from a fixed table.
Difference Between SPAN Margin and Exposure Margin
The difference between SPAN margin and exposure margin lies in what each one measures and how it is calculated.
| Feature |
SPAN margin |
Exposure margin |
| Purpose |
Covers the modelled worst case loss |
Adds a buffer for extreme moves |
| Basis |
Risk model with price and volatility scenarios |
Percentage of contract value |
| Portfolio effect |
Offsetting positions can reduce it |
Depends on applicable ELM rules and position-specific provisions |
| Changes |
Recalculated through the day |
Revised by the exchange from time to time |
How to Calculate SPAN and Exposure Margin?
It depends on which part is being worked out. SPAN needs the exchange’s risk files, so traders do not compute it manually and rely on the platform instead. The exposure part can be computed directly. Follow these steps for a single lot in futures trading.
- Note the lot size and the current price of the contract.
- Multiply the two to get the contract value.
- Apply the exposure margin percentage to the contract value.
- Read the SPAN amount from the broker’s margin calculator.
- Add the two amounts to get the total upfront margin.
SPAN Margin and Exposure Margin Formula
Exposure margin equals the percentage multiplied by the lot size and the market price of the contract. Total margin is then the SPAN amount plus the exposure amount.
Exposure margin = exposure percentage x lot size x price
Total upfront margin = SPAN margin + exposure margin
Worked Example
Let’s say a trader buys one Nifty futures lot at 24,500, where the lot size is 65 since January 2026. The exposure rate is taken as 2%, in line with the published base rate for index futures, and SPAN is assumed at 8% (for example).
| Component |
Calculation |
Amount |
| Contract value |
24,500 x 65 |
₹15,92,500 |
| SPAN margin (assumed) |
8% of 15,92,500 |
₹1,27,400 |
| Exposure margin |
2% of 15,92,500 |
₹31,850 |
| Total upfront margin |
1,27,400 + 31,850 |
₹1,59,250 |
Note: The above illustration uses assumed rates, because live SPAN values change through the day.
Platforms usually show the SPAN exposure requirement as one combined figure. If a hedged position, such as a calendar spread, is placed, the SPAN part can fall because the legs offset each other.
Peak Margin and Upfront Collection
Margin is not checked only at the end of the day. The clearing corporation takes four random snapshots of positions during the trading day, and the full SPAN plus exposure margin requirement must be met based on the highest margin requirement across these snapshots.
At least 50% of the total margin requirement must be maintained in cash or cash equivalents. The remaining requirement may be met through eligible non-cash collateral, subject to applicable exchange rules.
A trader who maintains only the minimum balance can therefore face a peak margin penalty, even if the position is closed before the market closes.
Factors That Change Margin Requirements
Several factors change the margin amount. A rise in volatility raises the SPAN scenarios, so margin often increases before major events. A higher contract price increases both parts. The type of contract also matters, since stock derivatives usually need more margin than index contracts. Option sellers need the largest margin among options traders, while buyers pay only the premium.
Managing Margin in Practice
A trader can manage margin by holding a balance above the requirement, checking the margin calculator before placing multi leg orders and avoiding a balance close to the minimum. Investors who want to buy shares with extra buying power can read about margin trading, which is a separate facility with its own rules.
Conclusion
SPAN margin covers the potential losses estimated through exchange risk scenarios, and exposure margin adds a buffer on top. Together they form the upfront deposit, and both change with volatility and contract price. A balance held above the requirement avoids rejected orders. Traders can open a Demat account with Religare and enable the derivatives segment to begin.
FAQs
Are SPAN and exposure margin added together?
Yes. The total upfront margin is the SPAN margin plus the exposure margin.
Who calculates SPAN margin?
NSE Clearing calculates the risk parameters, and brokers show the resulting margin for each position on their platform.
Can I reduce my SPAN margin?
Eligible offsetting positions, such as calendar spreads or hedged option legs, can lower the SPAN requirement.
Does exposure margin stay the same every day?
The rate is set by the exchange and revised from time to time, while the rupee amount also moves with price.
Is margin checked only at the end of the day?
No. Positions are checked several times during the day, and the highest requirement applies.